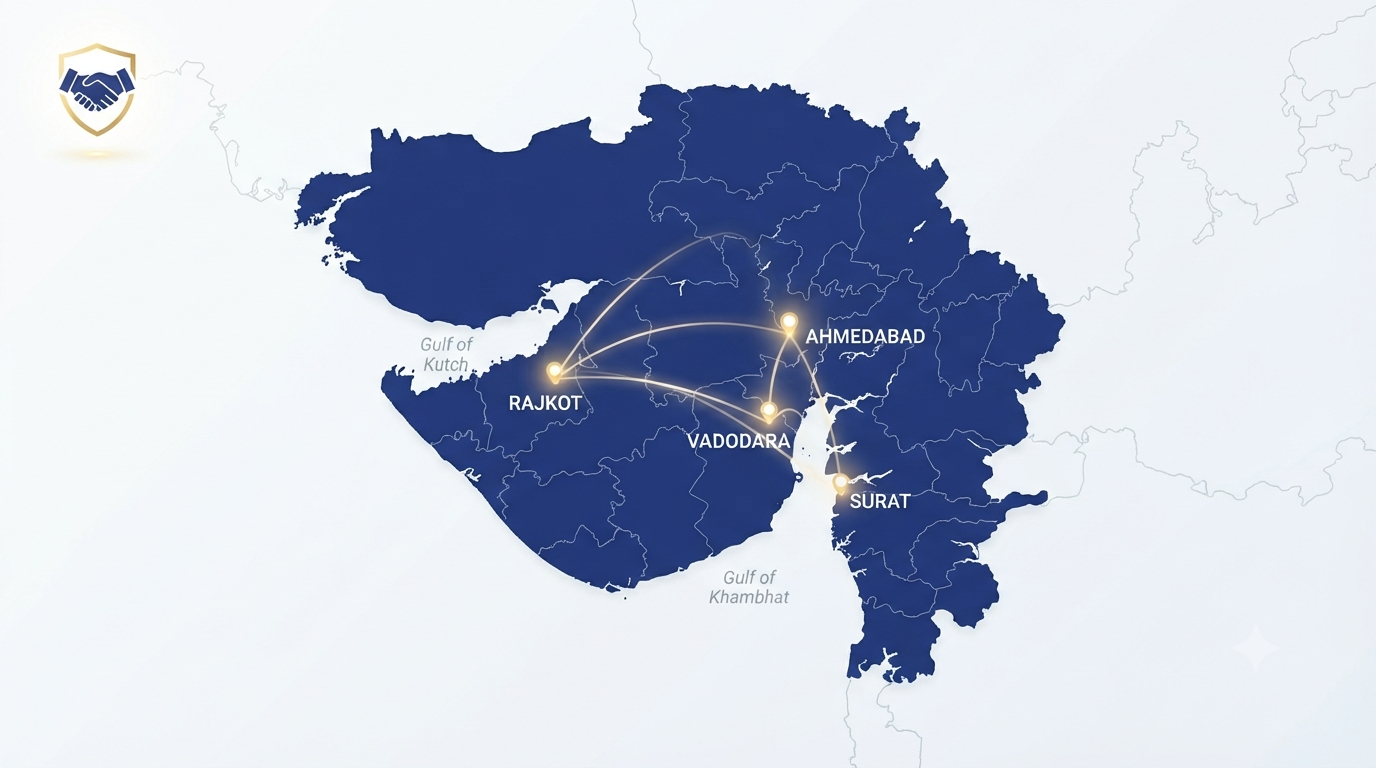
Quick answer: Under the CGTMSE scheme, MSMEs anywhere in Gujarat — Ahmedabad, Surat, Vadodara, Rajkot, Gandhinagar, and beyond — can access up to ₹10 Crore in business funding with zero collateral or third-party guarantee on the covered portion. For larger loans, banks can use a hybrid security structure, taking collateral only on part of the loan while the rest stays covered under the government guarantee. The guarantee itself typically covers 75%-85% of the default amount for the bank, rising to up to 90% for micro enterprises, women entrepreneurs, and specified regions.
CGTMSE Loan Limits Across Gujarat
Whether your business is based in Ahmedabad's industrial belt, Surat's textile and diamond processing units, Vadodara's chemical and engineering sector, or Rajkot's casting and auto-component cluster, the core CGTMSE limits apply state-wide:
- Loan Amount: Up to ₹10 Crore for eligible borrowers under standard guidelines
- No Collateral: Zero requirement for collateral security or third-party guarantees on the covered portion
- Hybrid Security: For larger loan requirements, lenders can take collateral on part of the loan while the remaining portion (up to the CGTMSE limit) stays unsecured under the guarantee
- Guarantee Coverage: Typically 75%-85% of the default amount to the bank, with higher coverage (up to 90%) available for micro enterprises, women entrepreneurs, and businesses in specified regions
Understanding Hybrid Security — Why It Matters for Larger Loans
Many Gujarat MSMEs assume CGTMSE only works for smaller, fully unsecured loans. In reality, for larger funding requirements, banks frequently structure a hybrid arrangement: part of the loan is secured against available collateral (property, machinery, or other assets), and the balance — up to the CGTMSE-eligible limit — is covered under the government guarantee without any additional security.
This matters because it means a Gujarat SME with some collateral but not enough to fully secure a large loan doesn't have to choose between a smaller fully-unsecured loan or a fully-secured loan requiring more property than they have. Hybrid security lets the bank extend a larger total facility while limiting its own risk exposure through the CGTMSE cover on the unsecured portion.
How Guarantee Coverage Percentage Works
The guarantee coverage isn't something the borrower receives directly — it's the percentage of the loan amount that CGTMSE reimburses the bank if the borrower defaults. This is why it directly affects how willing a bank is to sanction your loan without collateral:
| Borrower Category | Typical Guarantee Coverage |
|---|---|
| General MSME borrowers | 75%-85% of default amount |
| Micro enterprises | Up to 85%-90% |
| Women entrepreneurs | Up to 90% |
| Businesses in specified/priority regions | Up to 90% |
Higher coverage generally translates into faster approvals and better willingness from banks to extend larger unsecured limits, since their own downside risk is smaller.
Gujarat-Wide Coverage: City-by-City Relevance
| City/Region | Dominant MSME Sectors |
|---|---|
| Ahmedabad | Textiles, pharma, chemicals, auto-ancillary, engineering |
| Surat | Textile processing, diamond cutting & polishing, MMF (man-made fiber) |
| Vadodara | Chemicals, petrochemicals, engineering, pharma |
| Rajkot | Casting, forging, auto components, engineering goods |
| Gandhinagar & surrounding belt | IT, light manufacturing, ancillary units |
Regardless of sector, the CGTMSE eligibility framework — Udyam registration, business vintage, and financial documentation — applies uniformly across these regions.
Eligibility Snapshot
| Criteria | Requirement |
|---|---|
| Registration | Udyam (MSME) Registration Certificate |
| Loan amount covered | Up to ₹10 Crore under revised guidelines |
| Business type | New and existing units; manufacturing, processing, and most services eligible |
| Excluded activity | Retail trade is restricted/limited — verify against current CGTMSE notification |
| Credit profile | 700+ CIBIL preferred |
Documents Required
- Udyam (MSME) Registration Certificate
- PAN, Aadhaar, and business constitution documents
- Last 2-3 years financial statements (CA-certified or audited)
- GST returns — last 12 months
- Bank statements — 12 months, all current accounts
- Project report / business plan for new units or expansion
Frequently Asked Questions
Is CGTMSE available to MSMEs anywhere in Gujarat, or only in specific cities?
The scheme applies state-wide and nationally — CGTMSE-empanelled banks and NBFCs across Ahmedabad, Surat, Vadodara, Rajkot, and every other Gujarat district can extend the guarantee, as long as the borrower meets eligibility criteria.
What exactly is "hybrid security" under CGTMSE?
Hybrid security means a lender secures part of a larger loan with available collateral (property, machinery, etc.) while the remaining portion, up to the CGTMSE-eligible limit, is covered by the government guarantee without additional security — useful when a borrower has some but not enough collateral for the full loan amount.
Does higher guarantee coverage mean I personally get more money?
Not directly — the guarantee coverage percentage determines how much of a default the bank recovers from CGTMSE, not your loan amount. However, higher coverage (for micro enterprises, women entrepreneurs, or priority regions) often makes banks more willing to sanction larger unsecured amounts and approve faster.
Can a Surat diamond or textile processing unit use CGTMSE?
Yes, provided the business is Udyam-registered and falls under an eligible manufacturing/processing activity code — this is one of the most active CGTMSE sectors in Gujarat.
What is the maximum CGTMSE loan amount available in 2026?
Up to ₹10 Crore for eligible borrowers under the standard guidelines, though the actual sanctioned amount depends on the business's cash flow, financials, and the lending bank's own assessment.
How SME CFO Services Helps Gujarat MSMEs
- Hybrid vs. fully-unsecured structuring advice — matched to your available collateral and loan size requirement
- Multi-bank CGTMSE-empanelled submission across our 45+ partner network, spanning Ahmedabad, Surat, Vadodara, and Rajkot lending desks
- Category-based coverage optimization — checking eligibility for higher guarantee coverage (micro enterprise, women entrepreneur, priority region) to improve approval odds
Get a Free CGTMSE Eligibility Check
Wherever you're based in Gujarat, SME CFO Services offers a free, confidential CGTMSE eligibility assessment with a 48-hour preliminary feasibility report.
📞 +91 70147 40625 (Primary) | +91 96645 00277 (Secondary)
💬 WhatsApp Us | ✉️ smecfoservices@gmail.com
📍 406 Zodiac Plaza, Navrangpura, Ahmedabad 380006
SME CFO Services is an independent financial advisory firm and not a direct lender. CGTMSE guarantee cover, loan sanction, and fees remain at the sole discretion of the respective banks/NBFCs and the scheme's current guidelines.