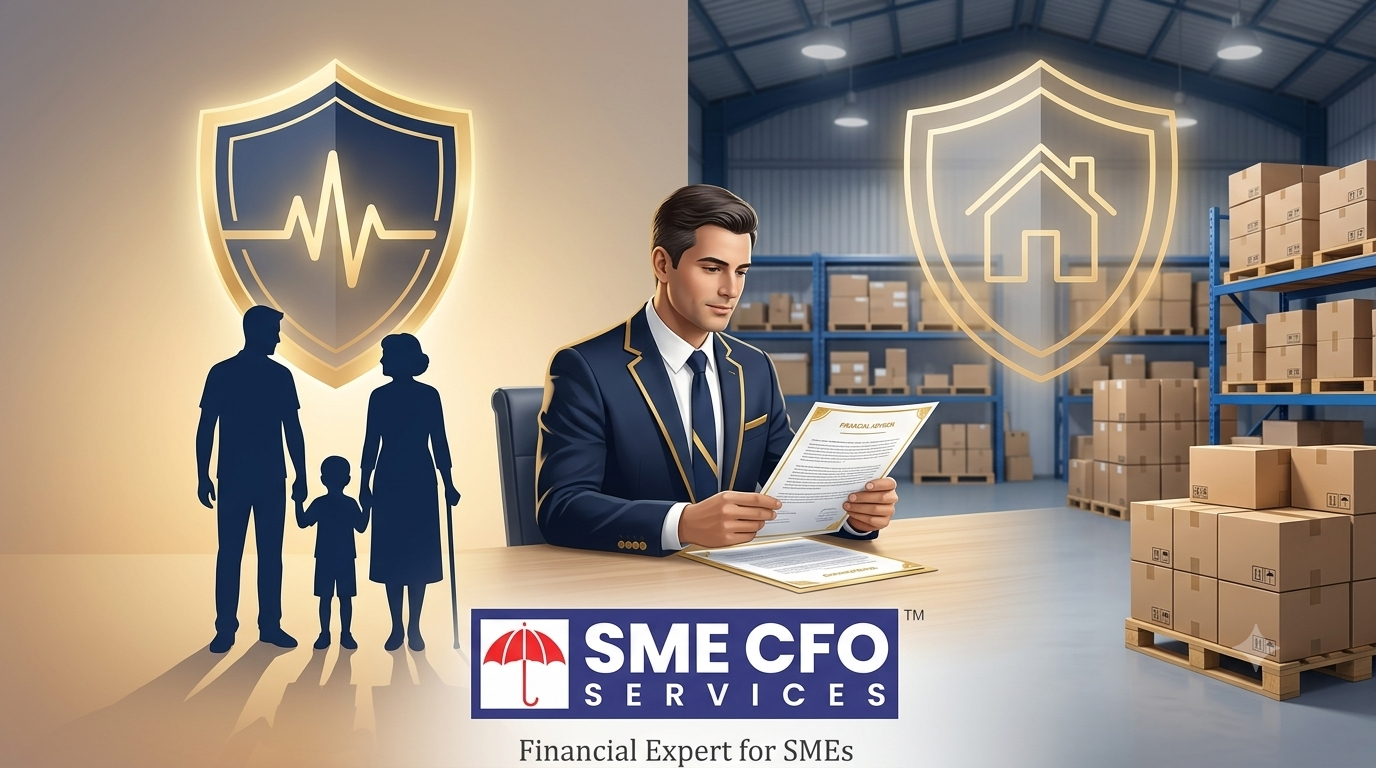
Here's a scenario that plays out more often than it should: a business owner takes a ₹1.5 crore Loan Against Property to expand operations, signs the paperwork, starts repaying — and never once considers what happens to that liability if something happens to them. The property stays mortgaged. The family inherits the EMI along with whatever the business leaves behind. Nobody planned for that outcome; it just happened because insurance was the thing that got pushed to "later" while the loan got all the attention.
Insurance has an image problem. It's sold aggressively enough, by enough people with a commission riding on it, that a lot of genuinely necessary cover gets lumped in with products nobody actually needs. The result is a kind of fatigue — people either over-buy complicated endowment plans they don't understand, or under-buy the simple, essential cover that would actually matter if something went wrong. Both are expensive mistakes, just in different directions.
Term Insurance: The One That Actually Matters Most
A term plan is about as unglamorous as insurance gets — no maturity bonus, no investment component, nothing to show for it if you're still alive when the policy ends. That's also exactly why it's efficient: your premium buys pure cover, not a bundled investment product with built-in fees. For a given sum assured, a term plan costs a fraction of what an endowment or ULIP would charge for similar life cover.
The sizing question matters more than people think. A common rule of thumb is 10-15 times annual income, but that's a starting point, not an answer — someone with ₹2 crore in outstanding business loans, a mortgage, and two children's education to fund needs meaningfully more cover than someone debt-free with grown children. The honest way to size it: add up what your family or business would need to survive without your income, plus whatever liabilities would otherwise fall on them, and work backward from there.
Loan Cover: The One Everyone Skips
This is the gap from the opening scenario. When you take a large secured loan — a LAP, a business term loan, a home loan — a loan cover policy ensures the outstanding balance gets paid off if something happens to you, so the liability doesn't transfer to your family or co-borrower along with whatever assets you're leaving behind.
Banks will sometimes offer this bundled with the loan itself, and it's worth being specific here: a bundled policy is convenient, but it's rarely the cheapest option, and the cover amount is tied rigidly to the loan's declining balance rather than your actual, broader protection need. Buying loan cover separately — sized to the loan, but as part of a wider term plan rather than a bank-bundled add-on — is usually both cheaper and more flexible.
Stock and Property Cover: The One Businesses Realise They Need Only After a Loss
If your business holds physical inventory, machinery, or operates from owned or leased premises, a fire or burglary policy covering stock and property isn't optional risk management — it's the difference between a bad month and the business not surviving at all. A warehouse fire that destroys ₹40 lakh of uninsured stock doesn't just cost ₹40 lakh; it can take down the whole operation, including whatever loans were serviced by that stock's eventual sale.
This matters even more for businesses that have taken a CC or OD limit against hypothecated stock — lenders will often require adequate insurance on the pledged stock as a condition of the facility, and letting that cover lapse can create problems with the bank quite separate from the actual risk of loss.
What This Looks Like Across Gujarat, Mumbai & Pune
Gujarat's manufacturing and trading base — textile units in Ahmedabad and Surat, chemical processors in Vadodara — carries significant stock and machinery value that's often underinsured relative to its replacement cost, particularly in businesses that have grown quickly and never revisited their cover amount to match.
Mumbai's density and property values mean both loan sizes and the cost of rebuilding or restocking after a loss are higher than almost anywhere else in the country, which makes adequate cover — rather than the cheapest available policy — genuinely worth the extra premium.
Pune's growing manufacturing and warehousing belt around the city has seen rapid expansion in recent years, and newer facilities in particular are sometimes insured based on original construction cost rather than current replacement value, leaving a gap that only becomes visible after a claim.
How to Actually Think About This, Rather Than Just Buying Policies
- Start with liabilities, not products — map out what loans, dependents, and business obligations actually need covering before picking any policy
- Separate protection from investment — a term plan for pure cover, kept distinct from any investment planning, is almost always more efficient than a bundled product trying to do both
- Revisit cover amounts as the business or loan grows — insurance bought three years ago against a smaller loan or smaller stock holding is quietly outdated the moment either grows
- Check what your lender actually requires — for stock/property-backed facilities, confirm your cover meets the bank's own conditions, not just your own sense of adequate
Questions People Ask
Is a term plan enough, or do I need an investment-linked policy too?
For pure protection, a term plan is generally the most efficient. If you also want to invest, that's usually better handled separately through mutual funds or other instruments, rather than bundled into an insurance product designed primarily for cover.
Do I need loan cover if I already have a term plan?
If your existing term plan's sum assured already accounts for your outstanding loan liabilities alongside your family's other needs, a separate loan cover policy may be redundant. The key is making sure the numbers actually add up, not assuming one automatically covers the other.
How much stock and property cover do I actually need?
Cover should reflect current replacement value, not original purchase or construction cost, and should be revisited whenever stock holding or property value changes meaningfully — an annual review is a reasonable habit.
Is bank-bundled loan insurance a bad idea?
Not necessarily bad, but rarely optimal — it's usually more expensive than buying equivalent cover separately, and the cover amount is rigidly tied to the loan balance rather than your actual protection needs.
What happens if my stock cover lapses on a loan where it's a lending condition?
This can create a separate problem with your lender beyond the insurance risk itself, since adequate cover is often a condition of the facility — it's worth treating renewal as seriously as any loan repayment deadline.
Where We Fit In
We look at insurance the way we look at everything else — as part of your overall financial picture, not a product sold in isolation. When we're structuring a large loan, we flag the loan cover gap at the same time, rather than leaving it as someone else's conversation later. If you want a straightforward review of what's actually covered versus what should be, that's a conversation worth having before, not after, something goes wrong.
Facebook | Instagram | LinkedIn
📞 +91 70147 40625 (Primary) | +91 96645 00277 (Secondary)
💬 WhatsApp Us | ✉️ smecfoservices@gmail.com
📍 406 Zodiac Plaza, Navrangpura, Ahmedabad 380006
Insurance is the subject matter of solicitation. Please read the policy wording and related documents carefully before concluding a sale. SME CFO Services provides financial advisory services and does not underwrite insurance policies directly; recommendations are made through our network of partner insurers/intermediaries and are subject to their own IRDAI-regulated terms and disclosures.